Infrastructure enabling rural finance.
SACCOs, microfinance institutions and savings groups run on our digital platforms. Our lending partnerships bring formal capital into the rural communities that need it most.
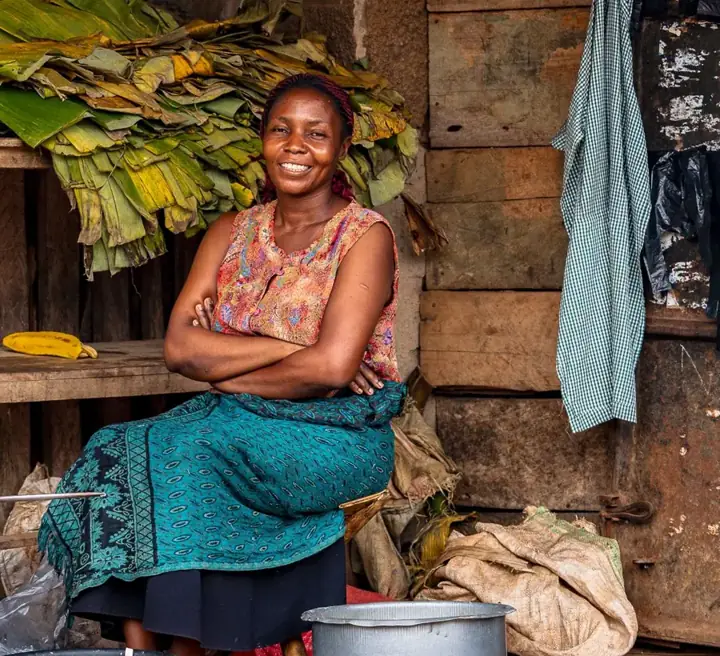
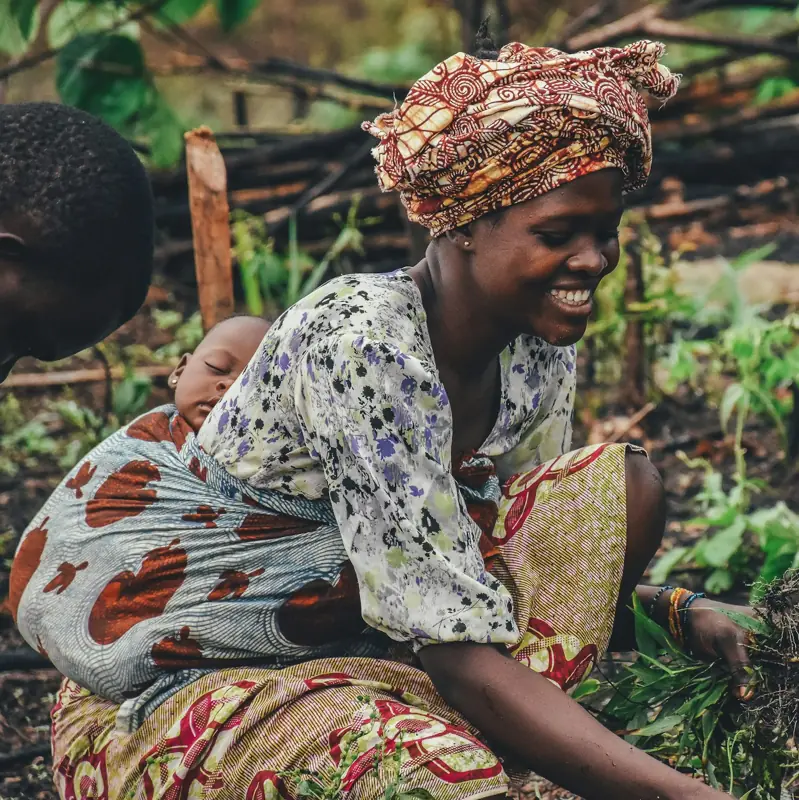
How bank capital reaches the village, and how it comes back.
Rural Africa already saves and borrows through SACCOs and savings groups. We give that system books a bank can read, and a rail its capital can travel on.
- Capital
Banks and funders
Commercial banks, development finance institutions and impact funds with capital to deploy, and no efficient way to reach rural borrowers.
- The rail
Ensibuuko
Mobis and Chomoka keep the books. Our lending rail underwrites on that record, disburses and collects.
- The lenders they trust
SACCOs, MFIs and savings groups
The community lenders rural people already save with, and already repay.
- Where it lands
Farmers, traders and women
Loans for inputs, stock and school fees, from the institution or group they already belong to.
Capital, priced on real repayment dataRepayments, and the record behind them
Two platforms. One record of how community finance behaves.
Institutions run their operations on Mobis. Savings groups run their meetings on Chomoka. Both write the operating data a lender can underwrite.
Core banking for SACCOs and microfinance institutions.
Customers, savings, loans, accounting and reporting on one ledger, across every branch, field officer and customer channel. Live since 2016, and serving 640,000 people through the institutions that run on it.
Visit Mobis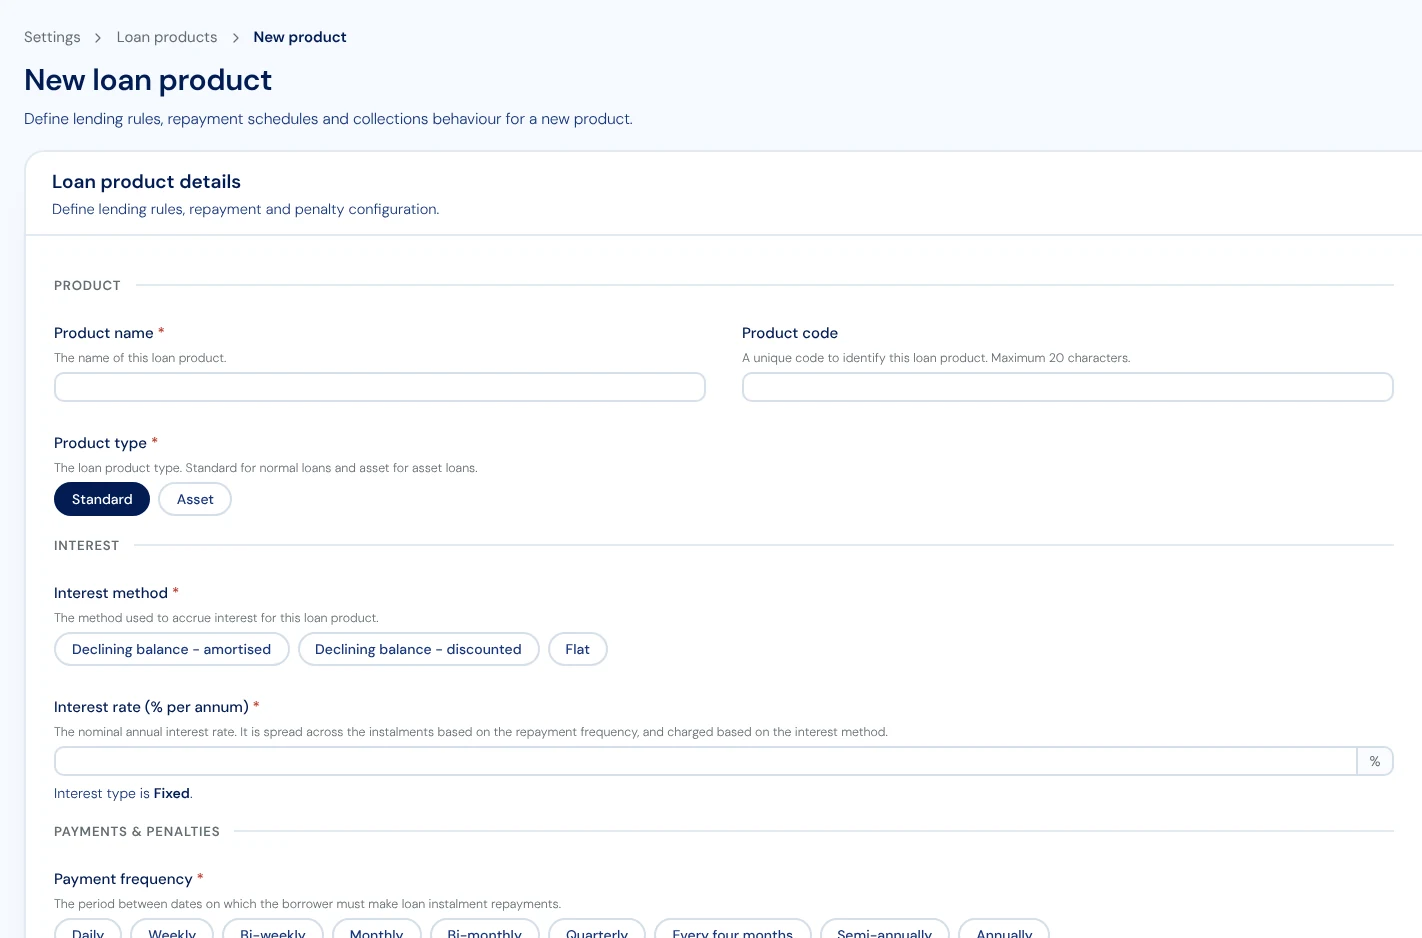
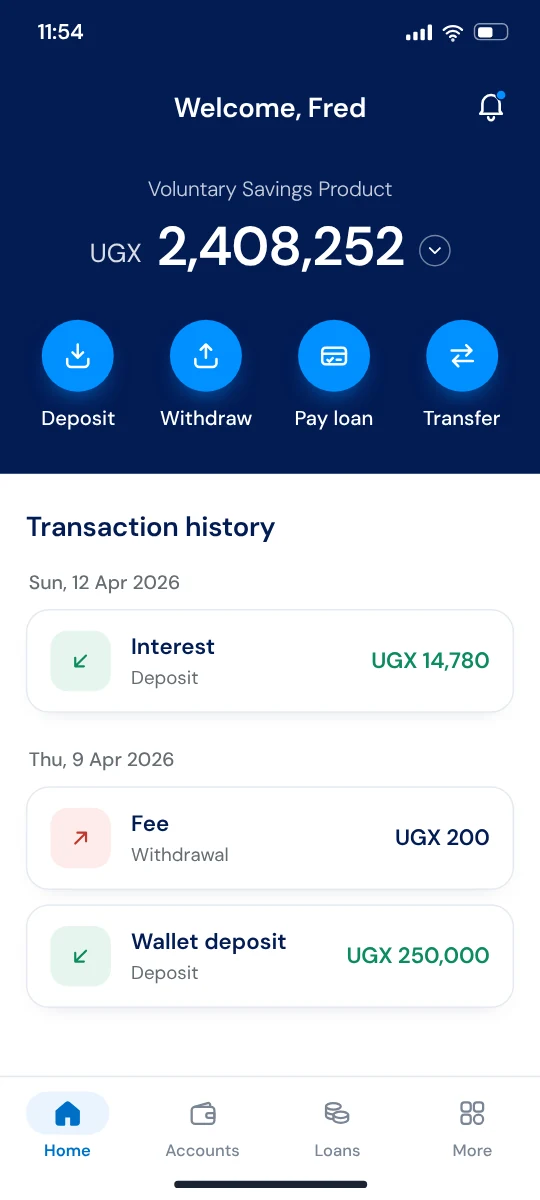
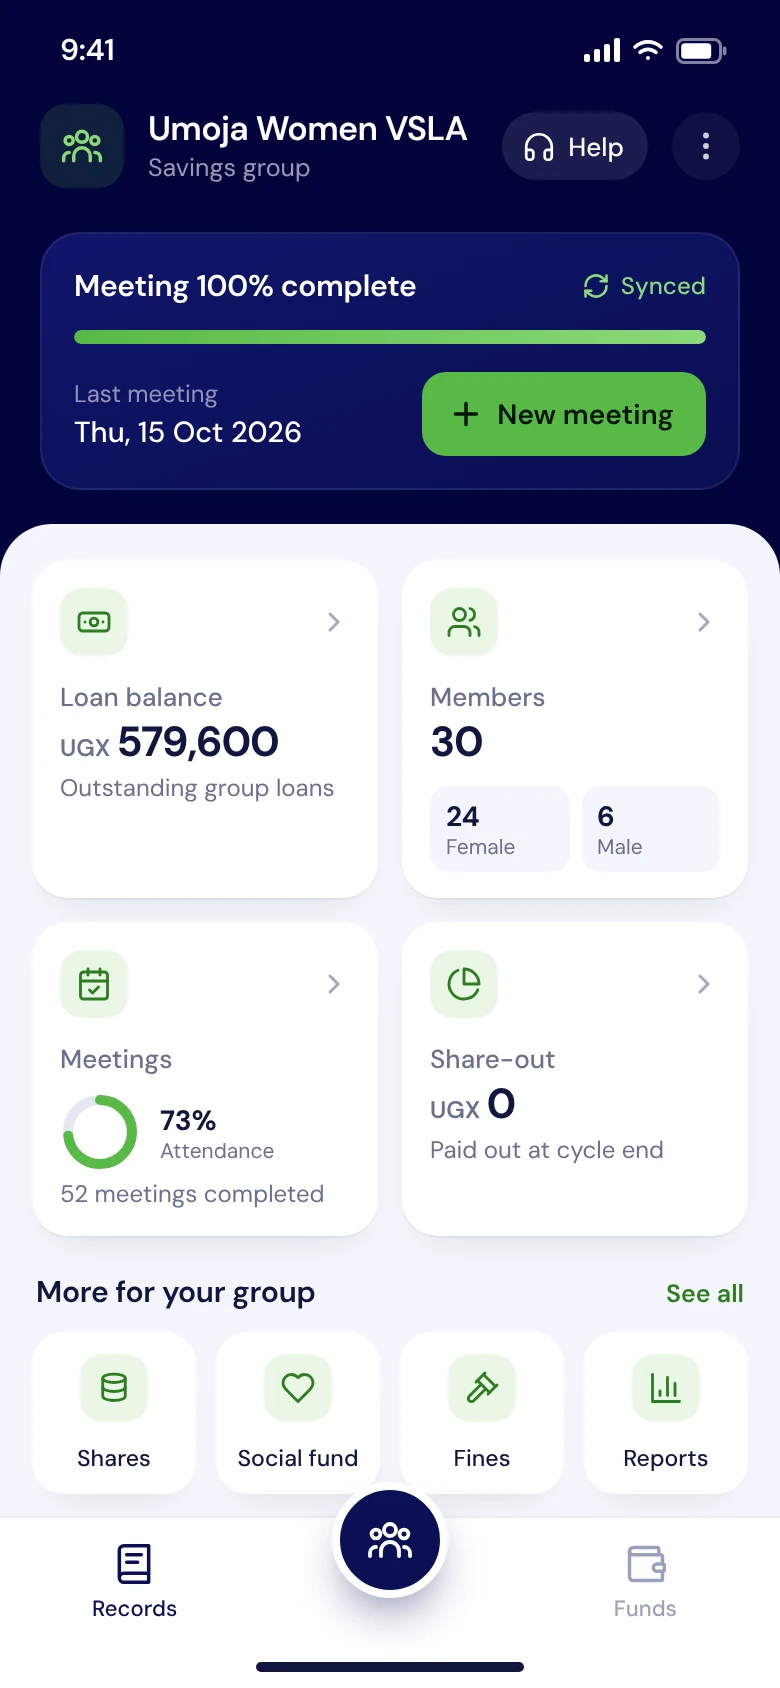
Savings groups on the record, and ready for credit.
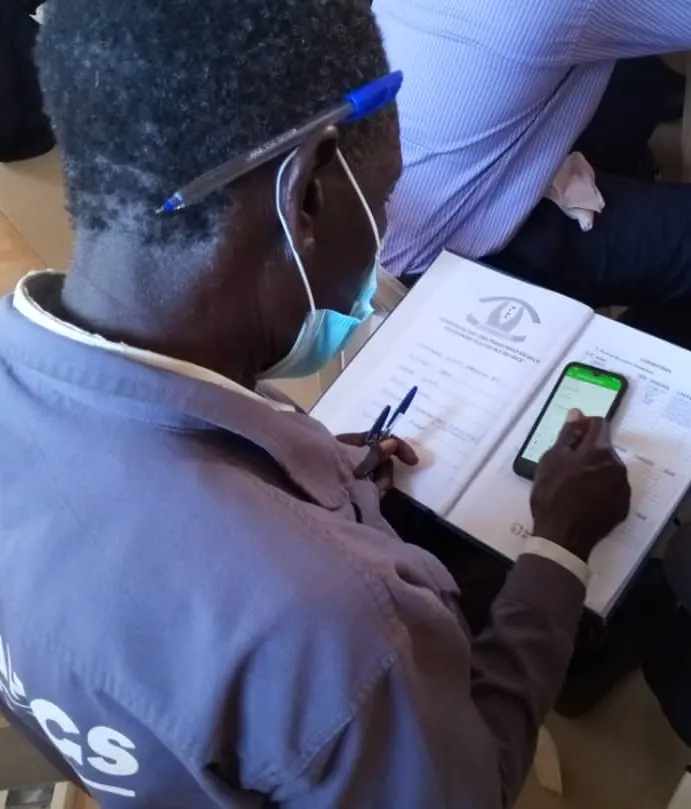
Groups record every meeting on one shared phone, with or without signal, and every member gets an SMS receipt. Development partners see the whole programme; lenders see a verified history they can lend against.
Acquired by Ensibuuko from CARE International. Visit Chomoka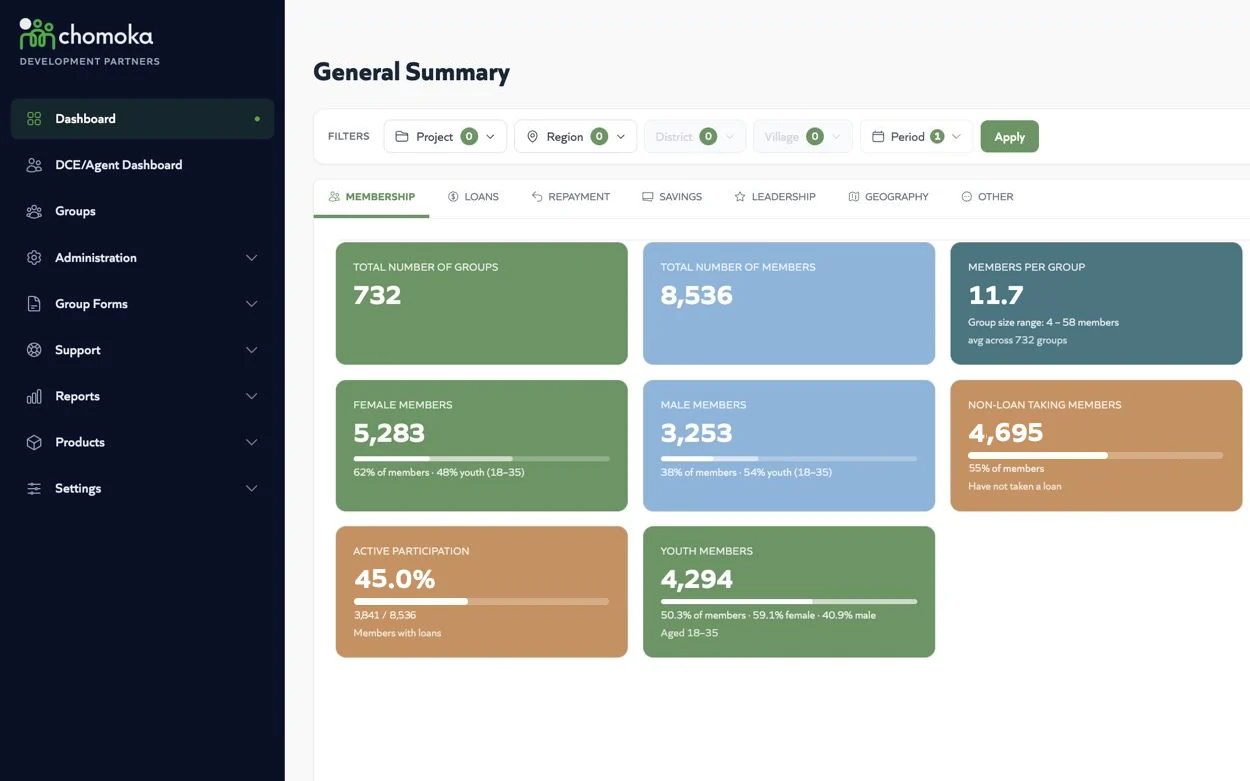
Both platforms settle over the rails people already use, so money and data move together.
Mobile money
- MTN MoMo
- Airtel Money
Deposits, repayments and disbursements, posted to the ledger as they land.
Channels
- App
- USSD
- SMS
- Agents
More than 200,000 people bank on their phones through our institutions.
Banks
- Settlement
- Wholesale credit
Bank transfers, and the capital partner banks deploy through our rail.
Credit bureau
- Licensed bureau
History checked at appraisal, and performance reported back.
APIs
- REST
- Webhooks
Server-to-server access for banks and partners who run their own systems.
Bank capital, delivered to the institutions and groups that already repay.
In 2023 we added a credit layer to our platforms. Partner banks provide the capital. We originate, disburse and monitor through the systems institutions and groups already use, against data recorded as the business happens, not reconstructed for a loan file.
- Capital
- Partner bank balance sheets
- Borrowers
- SACCOs, microfinance institutions and savings groups
- Underwriting
- Operating data from Mobis and Chomoka
- Disbursement
- Mobile money and bank rails
- Field support
- Digital Community Entrepreneurs
- Repayment rate
- 97.4%
- Licence
- Non-Deposit Taking Microfinance Company, 0442/NDT
Liquidity facility
A revolving facility of up to $100,000, drawn inside Mobis, so new disbursements do not wait for repayments to land.
Group loans
Loans of up to $10,000, paid into the group’s wallet and repaid meeting by meeting. Capital most groups could never reach before.
A lending channel
Reach hundreds of institutions and thousands of groups through one integration, with origination, disbursement and repayment data end to end.
Record
Institutions and groups run their daily operations on Mobis and Chomoka.
Score
Behaviour is scored with the lender’s credit team, on the lender’s product.
Disburse
Funds move to the institution or group wallet over mobile money or bank rails.
Monitor
Repayments are tracked as they land, so risk shows up before arrears do.
Credit is provided either by Ensibuuko Tech Limited, licensed by the Microfinance Regulatory Department under the Ministry of Finance as a Non-Deposit Taking Microfinance Company (licence 0442/NDT), or by the partner bank named in the loan agreement, under its own licence and credit policy. Where Ensibuuko lends to savings groups, it lends bank capital.
Four kinds of partner. One network between them.
Each side makes the others more valuable: institutions and groups generate the record, banks bring the capital, development partners bring the reach.
SACCOs and microfinance institutions
Core banking that gets you off spreadsheets, customer channels under your own name, and liquidity when collections run behind disbursements.
See MobisGroups and the networks that support them
A verified record of every meeting, SMS receipts for every member, and a route to formal credit sized to what groups need.
See ChomokaLenders who want to reach this market
A channel into thousands of creditworthy borrowers you could not serve efficiently, underwritten on real operating data.
Discuss a partnershipDonors, NGOs and government programmes
Digitise a savings group programme, report from live data instead of field spreadsheets, and deliver credit linkage that outlasts the grant.
Talk about a programmeBuilt in Uganda. Running in five African markets.
We go where community finance already works, and add the record and the capital it has been missing.
Uganda
Core banking, savings groups and lending, with field teams across the north, east and centre.
Tanzania
Built here by CARE International with savings group members in 2017.
Ghana
Savings group programmes digitised on Chomoka with development partners.
Malawi
Savings groups digitised with COMSIP, with digital group loans now disbursing.
Côte d’Ivoire
Savings group programmes digitised on Chomoka with development partners.
Regulated, certified and built to be audited.
Banks, regulators and development partners rely on our data. The controls they expect are on by default.
A licensed lender
Ensibuuko Tech Limited is licensed by the Microfinance Regulatory Department as a Non-Deposit Taking Microfinance Company. We do not take deposits.
Data that stays with its owner
Each institution owns its data, separated, encrypted and exportable. A savings group’s record reaches a lender only with that group’s consent.
Controls on by default
Role-based permissions, maker-checker on sensitive actions, and an audit trail of every posting, approval and change.
Built from the field up, since 2014.
Ensibuuko started in Kampala in 2014 with one observation: the institutions closest to underserved communities were running on paper. We built Mobis to give SACCOs real core banking, added a credit layer in 2023 so the data our platforms generate could unlock bank capital, and in 2024 acquired Chomoka from CARE International to bring savings groups onto the record.
Work with usThe questions partners actually ask.
Still unsure? Ask us directly in the form below.
What does Ensibuuko do? +
We build and run the digital infrastructure community finance operates on: Mobis, core banking for SACCOs and microfinance institutions, and Chomoka, the platform savings groups record their meetings on. On top of both we run a lending rail that brings partner bank capital to those institutions and groups, underwritten on the operating data the platforms generate.
How are Mobis and Chomoka related to Ensibuuko? +
Both are Ensibuuko products. Mobis has been built and run by Ensibuuko since 2016. Chomoka was built by CARE International, starting in Tanzania in 2017; Ensibuuko acquired it in 2024 and now develops, hosts and operates it, with CARE as a long-term strategic partner.
Is Ensibuuko a bank? +
No. Ensibuuko Tech Limited is licensed by the Microfinance Regulatory Department under the Ministry of Finance as a Non-Deposit Taking Microfinance Company, licence 0442/NDT. We do not take deposits. The capital we deploy comes from partner banks.
Who carries the credit risk? +
Where a partner bank lends through our rail, the bank lends under its own licence and credit policy and carries the risk on its loans. Where Ensibuuko extends a facility to an institution, the institution is our borrower. Institutions continue to lend to their own customers under their own licence; we take no part in those decisions.
Does an institution have to borrow to use Mobis? +
No. Lending is optional and non-exclusive. The software agreement and any credit agreement are separate, and neither is conditioned on the other.
How do you reach savings groups in rural areas? +
Through Digital Community Entrepreneurs, trained agents from the communities they serve, supported by our field offices across Uganda. The Chomoka app works fully offline on one shared phone per group and syncs when it finds a connection, and members receive SMS receipts on any handset.
Where do you operate? +
Uganda, Tanzania, Ghana, Malawi and Côte d’Ivoire. Lending is live in Uganda, and digital group loans are disbursing in Malawi with COMSIP. In the other markets we digitise savings group programmes with development partners.
Who owns the data, and how is it protected? +
Each institution owns its data and can export it in full at any time. A savings group’s record is shared with a lender only with that group’s consent. Data is separated per institution, encrypted in transit and at rest, and processed under the data protection law of each market; in Uganda we are registered with the Personal Data Protection Office, PDPO-202205-0334.
How does a bank integrate? +
Either through our loan management portal, as it is, or by connecting your own core banking or loan system to ours over a server-to-server API. Disbursement and collection run over mobile money and bank rails, and portfolio data flows back as repayments land.
How do we start working together? +
Use the form below or email partnerships@ensibuuko.com. For a Mobis demo, write to sales@ensibuuko.com. For careers, write to info@ensibuuko.com.
Tell us what you are lending, running or building.
Banks and capital partners, institutions, development partners: a real person reads every message.
Discuss a partnership
Tell us who you are and what you want to do. We will come back to agree a time.
We usually reply within one working day